How Canada’s SR&ED Should Affect Your Startup’s Tax Planning
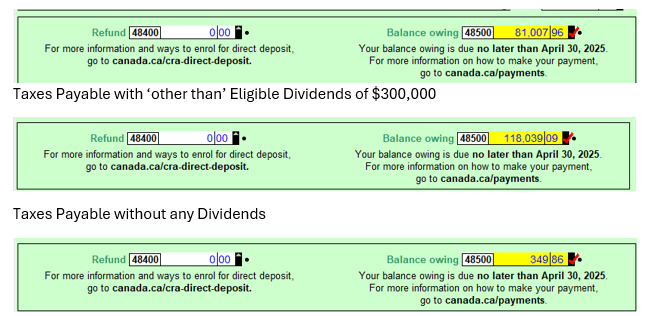
by Rob Farrow, SBA (www.suttoninnovation.com) As an SR&ED tax specialist working with micro-businesses doing eligible experimental development, I have noticed a tendency among practitioners at small and medium-sized CPA firms to rely on traditional income-versus-dividend analyses for tax planning. However, because eligible salaries for development teams can typically result in refundable investment tax credits of … Read more