by Rob Farrow, SBA (www.robfarrow.net)
According to an article published in June of 2026 in The Globe and Mail, Canadian startups struggle to pass the ‘valley of death’. It’s a familiar refrain of so-called ‘experts’ and ‘influencers’. In this case, a poorly researched study was delivered to Canada’s Senate. Predictably, the authors were supporting more taxpayer funding for investor groups in early-stage companies.
Here are the core takeaways from the article:
Core Problem: Canada’s “Valley of Death” in Startup Financing
- Canadian startups face a severe funding gap between $5M and $25M, the stage where companies must scale.
- Early-stage capital (small rounds) and late-stage capital (tens of millions) exist — but growth capital is missing.
- This gap causes firms to stagnate, sell early, or relocate abroad, worsening Canada’s long-standing productivity crisis.
Structural Weaknesses in Canada’s Capital Market
- OECD data places Canada near the bottom for SMB lending volume and loan size.
- Growth-stage investment in Canada recently fell to near zero.
- Entrepreneurs report:
- Slow timelines (6–12 months for BDC or traditional bank loans).
- Higher interest rates for SMBs than in other OECD countries.
- Follower capital dominates — investors wait for foreign validation before investing.
Real-World Examples
- Ranovus (AI semiconductor firm): Only 17% of its US$160M raised came from Canadian investors; had to go to California for growth capital.
- Ubiweb Media: Lost opportunities because Canadian lenders took too long.
- Eddyfi Technologies: Sold for ~$2B to a U.S. buyer because no Canadian buyer could finance the acquisition.
Senate Committee Efforts
The Senate banking committee is preparing a report after months of testimony. Key themes:
- Canada’s innovation funding ecosystem is fragmented across 130+ federal programs with little strategic coherence.
- Current federal support (~$4.5B/year) is piecemeal and doesn’t incentivize private-sector participation.
Proposed Solutions
- Canadian Private Debt Growth Fund
- Pension funds contribute large pools of capital.
- Private lenders deploy loans (e.g., $15–30M) and share risk.
- Ottawa guarantees part of the pension fund exposure.
- New SME-Focused Banks
- Tax & Regulatory Incentives
- CSSC designation (Canadian Sovereign Scalable Company) with:
- 30% refundable federal tax credit (stackable with provincial credits).
- Capital gains deferral if reinvested in another CSSC.
- Flow-through shares expanded beyond mining to tech, agriculture, AI, etc.
- U.S.-style QSBS exemption for capital gains on small business stock.
- CSSC designation (Canadian Sovereign Scalable Company) with:
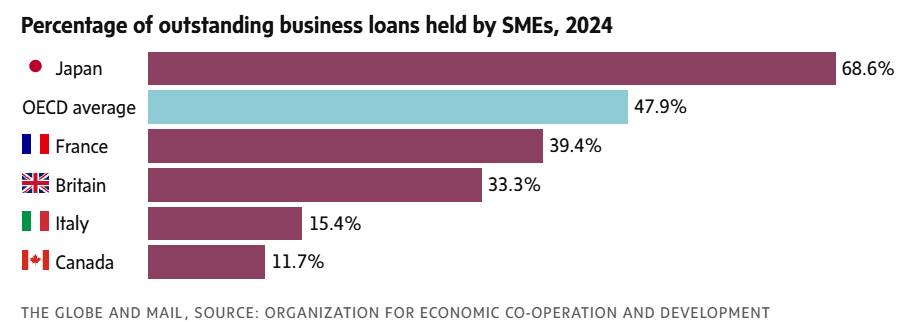
Problems with the Globe’s Analysis
Data from the Organization for Economic Co-operation and Development ranks Canada third from the bottom among developed countries in terms of both percentage of small- and medium-sized business lending as a share of total lending and of absolute value of loans per capita. Does this data suggest that Canadian small and medium-sized have more trouble getting financing, or that they use different kinds of financing?
Short answer: The OECD data does not imply that Canadian SMEs face unusually severe financing barriers. Instead, it strongly suggests that Canadian SMEs rely on a different mix of financing instruments, with bank loans playing a smaller role than in many peer countries. This interpretation aligns with broader OECD findings that SME loan stocks are stagnant globally, while alternative instruments—leasing, factoring, government-backed loans, and fintech credit—are increasingly important.
Canada’s low SME-loan share reflects financing structure, not necessarily financing difficulty. Canadian SMEs appear to use more non-bank and government-backed instruments, and less traditional bank debt, compared to SMEs in other OECD economies.
OECD reports show sluggish SME loan growth globally—not uniquely in Canada
The 2026 Scoreboard notes that SME loan stocks are “broadly stagnant” across nearly 50 countries, with banks applying stringent terms amid economic uncertainty. This is a global pattern, not a Canada-specific failure.
Canadian SMEs increasingly use non-bank finance
OECD highlights a growing role for fintech lenders, asset-based financing, leasing, and factoring in SME financing. These instruments don’t show up in “SME bank lending share” metrics, which makes Canada look under-leveraged even when SMEs finance themselves through other channels.
Canada’s SME financing profile is shaped by its banking structure.
Canada has a highly concentrated banking sector with conservative underwriting standards. This pushes SMEs toward government-backed loans, tax credits (SR&ED), leasing, and alternative lenders, which reduces the share of SME bank loans in aggregate lending statistics—even when SMEs are adequately financed through other channels.
EDITOR’S NOTE
Unicorns per capita in G7 Countries
When measured properly, Canada performs better than every G7 country except the United States and the United Kingdom in unicorns per million population. The latest global unicorn counts confirm this pattern clearly.
| G7 Country | Approx. Population | Average New Unicorns Minted Per Year | Annual Unicorns Created Per 10 Million People |
| United States | 335 Million | ~100 – 108 | 3.0 to 3.2 |
| United Kingdom | 67 Million | ~8 – 10 | 1.2 to 1.5 |
| Canada | 39 Million | ~4 – 6 | 1.0 to 1.5 |
| France | 68 Million | ~3 – 4 | 0.4 to 0.6 |
| Germany | 84 Million | ~3 – 4 | 0.3 to 0.5 |
| Italy | 59 Million | ~0 – 1 | Under 0.1 |
| Japan | 125 Million | ~1 – 2 | Under 0.1 |
G7 Percent of Firms by Common Firm Size
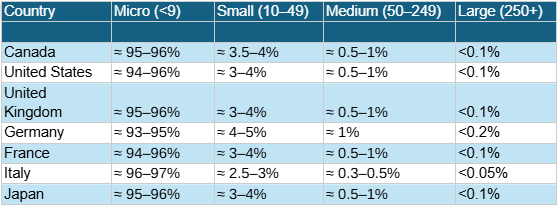
What’s more, all G7 countries (even the US) are dominated by businesses with fewer than 10 employees.
Despite this, the business press, business schools, and policymakers (eg., senators) benefit from what social psychologist Robert Cialdini called BIRGing (basking in reflected glory), or increasing their own public image by associating themselves with the success of others – even though they played no part in that success.
https://en.wikipedia.org/wiki/Basking_in_reflected_glory
Do we need more government incentives and risk-sharing that benefits venture capital firms?
“It all “leads to a type of stagnation, where companies don’t outright fail, but they don’t prosper either,” Hans Knapp, co-founder of Vancouver-based venture capital firm Yaletown Partners Inc., recently told a hearing of the standing Senate committee on banking, commerce and the economy.”
Yaletown Partners Inc. benefits from a 30% VCC credit for investing in its tech company targets. Do they need another federal tax credit to stack on top of that credit? Perhaps we should also get the government to provide additional ‘risk-sharing’ as well as tax deferrals on capital gains – beyond the current lifetime capital gains deductions for eligible CCPCs?
Perhaps it’s time to shift our policies away from industries that are most likely to depend on massive US markets and deep US-based VC funding pools for scaling. In the 1980s Australia abandoned the dream of manufacturing in favour of resources and agriculture for growth. Perhaps it’s time that Canada did the same.